
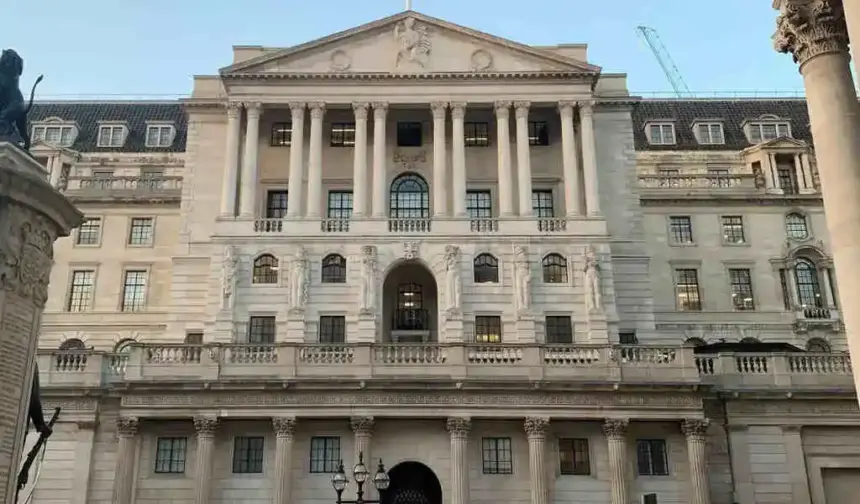
LONDON – The Bank of England has warned lenders that their loan loss models carry “elevated” risk. It also criticised banks for not fully accounting for how high inflation and interest rates affect borrowers’ ability to repay.
Although rising rates have added to the cost-of-living pressures facing UK households, which owe about £22 billion in essential expenses, banks have kept loan loss provisions relatively low.
In a letter sent on Friday to finance chiefs at nine major banks, Vicky Saporta, the Bank of England’s head of prudential regulation, said some models were not properly calibrated to reflect the effects of higher inflation and interest rates on borrowers.
Since 2018, accounting rules have required banks to set aside funds for possible future defaults. As a result, lenders estimate expected loan losses rather than waiting to record losses after borrowers default.
Bank supervisors expect these forecasts to reflect both current economic conditions and banks’ past performance during periods of financial stress. Saporta said lenders should review adjustments made outside their models and check whether provisions match their expected credit losses.
The Bank also told lenders to test whether their models account for affordability risks, including the pressure that rising prices and borrowing costs place on financially vulnerable customers.
Bank of England held interest rates at 5.25%
After nearly two years of rate increases, the Bank of England kept its base rate at 5.25% in September to bring inflation down. The Office for National Statistics reported that UK inflation was 6.7% in August.
Saporta also raised concerns about banks’ estimates of how much they could recover from bad loans, often through selling assets used as collateral. She urged lenders to assess vulnerable areas of their businesses and consider more severe, but plausible, economic scenarios involving higher inflation and interest rates.
The Bank of England has repeatedly warned that rising debt leaves households and businesses vulnerable, even though defaults remained low in 2023.
In 2022, the Bank also reviewed how lenders assessed climate-related risks. It found that banks had made progress but still faced major obstacles. Saporta said poor data availability and quality remained widespread problems, and added that banks could benefit from centralising data collection because their approaches to climate analysis were fragmented.