
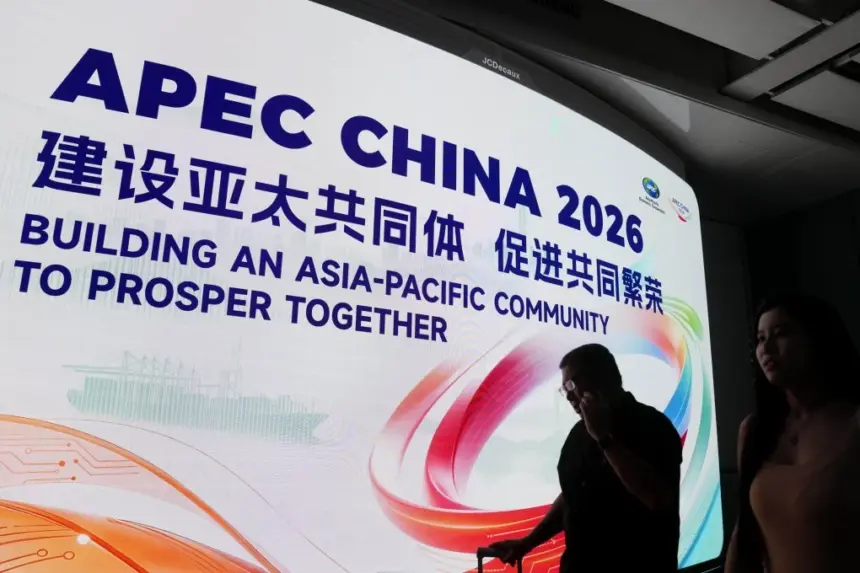
SHENZHEN, China — China’s domestic economy stumbled badly in October, with retail sales barely budging and business investment plunging just days before President Xi Jinping welcomes world leaders to the southern tech hub of Shenzhen for the Asia-Pacific Economic Cooperation summit.
Official figures released Monday by the National Bureau of Statistics show retail sales edged up just 0.4% from a year earlier, fixed-asset investment tumbled 8.1% across the first ten months of 2026 and industrial output growth cooled to 4.8%. The sharp slowdown leaves the world’s second-largest economy leaning heavily on overseas buyers to absorb factory goods, sharpening trade friction with Washington and Brussels as Xi prepares to host 21 Pacific Rim leaders.
Key Takeaways• China’s October retail sales rose just 0.4% year-on-year, fixed-asset investment dropped 8.1% over ten months and industrial output growth slowed to 4.8%. • Weak home spending has forced Beijing to rely on overseas markets, driving a trade surplus above $1 trillion in 2026. • Premier Li Qiang courted Southeast Asian partners in Manila while President Xi Jinping prepares to host APEC leaders in Shenzhen amid tariff tensions. |
Shoppers Pull Back as Factory Floors Cool
Chinese households kept their wallets shut in October. The 0.4% year-on-year gain in retail sales marked a steep drop from September’s 1.1% pace and missed private economists’ consensus forecast of 0.8%. On a monthly basis, consumer spending was virtually flat, underscoring how cautious families remain despite repeated government pledges to spark consumption.
Discretionary purchases took the hardest hit. Big-ticket items such as household appliances, furniture, cosmetics and jewelry saw tepid checkout traffic across major urban shopping districts, while restaurant receipts grew only modestly. Even autumn holiday travel failed to deliver the sustained spending bounce retailers had banked on heading into the fourth quarter.
Factories also lost speed. Value-added industrial output expanded 4.8% in October compared with a year earlier, down from September’s six-month high of 5.5% and below analysts’ expectations of 5.3%. While high-tech equipment and semiconductor lines posted brisk gains, traditional manufacturing—including steel, cement and basic textiles—struggled under sluggish domestic orders and falling factory-gate prices.
Business capital spending painted an even darker picture. Fixed-asset investment—a broad gauge covering infrastructure, real estate, machinery and factory equipment—contracted 8.1% during the January-through-October period. That decline deepened from a 7.2% drop across the first nine months of the year, signaling that private companies remain reluctant to commit fresh cash to domestic expansion.
Even the lone bright spot in Monday’s statistical bulletin carried caveats. The surveyed urban unemployment rate edged down to 5.1% in October from 5.2% in September, reaching its lowest level since June. Yet new home prices across 70 major cities fell 2.4% year-on-year, extending a housing slump into its 40th consecutive month and eroding the primary store of wealth for millions of middle-class households.
A Trillion-Dollar Surplus Fueled by Weak Home Demand
With domestic buyers sitting on the sidelines, Chinese manufacturers have turned aggressively toward foreign ports to keep assembly lines running. Customs data released earlier this month showed China’s trade surplus surpassed $1 trillion for the second straight year, propelled by surging shipments of semiconductors, electric vehicles, solar panels and industrial machinery.
Semiconductor exports alone jumped 137.1% by value in October compared with a year earlier, while outbound auto shipments climbed 37.6%, according to Chinese customs figures. Those numbers highlight the sheer scale and cost competitiveness of China’s industrial supply chains, which continue to capture global market share even as Western governments erect higher tariff walls.
That export surge carries steep political risks. Trading partners in North America, Europe and parts of Asia have warned that a flood of low-cost Chinese goods threatens their own domestic industries. When domestic demand stagnates inside a manufacturing superpower, excess capacity inevitably spills across borders—turning an internal economic imbalance into an international trade dispute.
Export-dependent coastal provinces also face growing vulnerability to shifts in global tech spending. Analysts note that China’s recent boom in chip and electronics shipments relies heavily on global artificial intelligence infrastructure buildouts, leaving Chinese suppliers exposed if Western data center investment cools in 2027. Container shipping rates out of Shenzhen’s Yantian port and Ningbo have already begun fluctuating sharply as overseas importers front-load orders ahead of potential new tariff deadlines.
Inside the Structural Roots of China’s Demand Slump
To understand why October’s numbers missed forecasts so widely, economists look below the headline percentages to three structural bottlenecks weighing on China’s post-pandemic economy: a prolonged property hangover, debt-strapped local governments and a lopsided industrial policy.
For nearly two decades, real estate and municipal infrastructure served as China’s primary growth engines, accounting for roughly a quarter of gross domestic product. Since Beijing tightened borrowing rules on property developers in 2020 to deflate a speculative credit bubble, unfinished apartment towers and falling land sales have starved local governments of revenue. Without land-sale proceeds, provincial authorities have slashed spending on roads, bridges and public utilities—directly dragging fixed-asset investment into negative territory throughout 2026.
At the same time, Beijing has funneled hundreds of billions of dollars in state-backed bank loans into advanced manufacturing—batteries, robotics, chips and green energy—rather than direct cash transfers or social safety net expansions for households. Economists call this supply-side tilt an investment-heavy growth model. It builds world-beating factories, yet leaves ordinary workers saving a high share of their income to cover health care, elder care and education costs.
Wage stagnation across the private sector has compounded that caution. Private enterprises employ roughly 80% of China’s urban workforce, yet weak profit margins and regulatory uncertainty have led many small and midsize firms to freeze hiring or trim year-end bonuses. Young graduates entering the job market face fierce competition for entry-level roles, prompting families to prioritize paying down mortgages and building emergency cash reserves rather than upgrading cars or electronics.
On the ground in southern manufacturing hubs like Dongguan and Shenzhen, the divergence is visible in daily operations. Export-oriented electronics plants run double shifts to fill overseas orders ahead of holiday deadlines and potential tariff hikes, while domestic furniture makers, appliance dealers and mid-tier retail malls offer steep discounts just to clear inventory. A two-month extension of a bilateral tariff truce with Washington until January has bought exporters temporary breathing room, though Shenzhen cross-border e-commerce associations report rising compliance costs and tighter customs scrutiny in both U.S. and European ports.
Diplomatic Push From Manila to the Pearl River Delta
Faced with mounting trade friction in the West, Beijing is working overtime to lock in friendly commercial corridors closer to home. On Monday in Manila, Premier Li Qiang met Southeast Asian leaders at the 29th ASEAN-China Summit, marking five years since the two sides upgraded ties to a Comprehensive Strategic Partnership.
Speaking alongside Philippine President Ferdinand Marcos Jr., Li praised regional trade resilience against what he described as rising unilateralism and protectionism. Leaders at the Manila gathering adopted a joint statement and backed an ASEAN-China Plan of Action running through 2030, aimed at streamlining customs clearance, expanding digital trade links and protecting regional supply chains.
Southeast Asia has become China’s largest regional trading partner, absorbing massive volumes of Chinese intermediate components that are assembled into finished goods across Vietnam, Malaysia, Thailand and Indonesia before shipping worldwide. Keeping those trade lanes open is vital for Beijing as Western buyers diversify supply chains away from mainland ports. At the same time, several Southeast Asian governments have begun imposing targeted anti-dumping duties on Chinese steel, plastics and textiles to shield their own local factories from low-priced imports.
Diplomatic momentum now shifts immediately north to Shenzhen, where Xi will host the APEC Economic Leaders’ Meeting on Nov. 18 and 19. The 21 member economies of the Asia-Pacific Economic Cooperation forum generate roughly 61% of global gross domestic product and nearly half of world trade.
High Stakes on the Sidelines in Shenzhen
Choosing Shenzhen as the host city carries unmistakable symbolism. Four decades ago, Shenzhen was a cluster of fishing villages across the border from Hong Kong before Deng Xiaoping designated it China’s first Special Economic Zone, transforming it into the flagship laboratory of China’s export-led economic miracle.
Today, Shenzhen is home to technology giants including Huawei, Tencent and electric vehicle maker BYD—companies that embody Beijing’s push for technological self-reliance. By bringing APEC leaders to the Pearl River Delta, Xi aims to showcase China’s industrial modernization while pitching Beijing as a steady defender of open, multilateral commerce.
Yet the summit’s real drama will unfold in bilateral meetings behind closed doors. Xi is scheduled to meet U.S. President Donald Trump on the sidelines of the Shenzhen gathering, with tariffs, semiconductor export controls and bilateral trade imbalances topping the agenda. Emerging economies such as Indonesia are also pressing Beijing and Washington alike to preserve open market access and prevent trade bloc fragmentation.
Back home, Beijing’s economic planners face a narrowing window to stabilize domestic growth before year-end. In its Monday statement, the National Bureau of Statistics acknowledged that domestic demand remains insufficient and that many enterprises continue to face operational strain, pledging faster rollout of supportive fiscal and monetary policies.
Economists say Beijing has room to trim bank reserve requirements, expand consumer trade-in vouchers for appliances and cars and accelerate special bond issuance to help local governments clear unpaid bills to private contractors. Even so, commercial banks remain cautious about lending to heavily indebted municipalities and struggling property developers, dulling the impact of central bank rate cuts.
Whether those incremental steps can revive household confidence remains an open question. Until Chinese shoppers start spending again at home, Beijing’s trillion-dollar export engine—and the global trade tensions it fuels—will remain front and center across the Pacific Rim.