
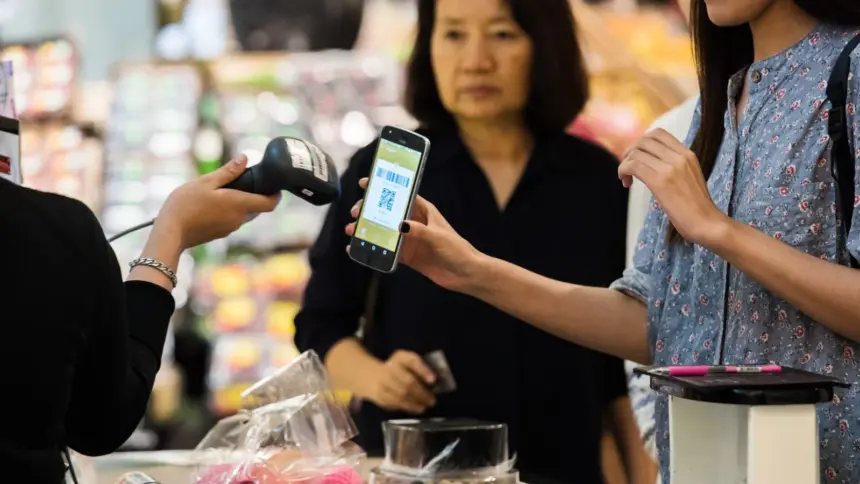
A customer at a Bangkok shop scans a QR code, confirms the amount in a banking app, and pays without reaching for cash. For small businesses across Thailand, digital payments now affect how money comes in, how sales are recorded, and how customers check out.
These tools can make transactions easier to track and offer customers more convenient ways to pay, but fees and settlement terms vary. The right setup depends on where you sell and which payment methods your customers prefer. Here’s how Thailand’s digital payments ecosystem is changing everyday business transactions.
Key Takeaways
- Digital payments give Thai small businesses another way to accept customer payments and manage everyday sales.
- PromptPay QR lets customers pay through mobile banking apps, as explained in the Bank of Thailand’s PromptPay guide.
- Digital transaction records can help owners review incoming payments and reconcile sales with business accounts.
- Fees, settlement timing, and transfer limits vary by payment method and provider, so check the terms before choosing PromptPay for business payments.
- The best payment setup depends on customer preferences, sales channels, and the costs a business can manage.
How Digital Payment Systems Are Changing Small Business Transactions in Thailand
Digital payments give small businesses more ways to take payment during everyday sales. The change is especially visible at checkout, where customers can pay by scanning a QR code, tapping a card, or using an accepted mobile wallet.
From cash to PromptPay and Thai QR payments
With PromptPay and Thai QR Payment, a customer scans a merchant’s code in a participating banking app, checks the payment details, and confirms the transfer. Thailand’s standardized QR format lets participating apps read compatible merchant codes, so a stall or shop may not need separate codes for every bank. The Bank of Thailand’s Thai QR payment standard outlines the format behind this system.
For market stalls, restaurants, and small shops, QR payments can require little equipment beyond a printed code and a phone or other way to confirm payment. That can be practical for a vendor taking orders at a busy market or a cafe collecting payment at the counter. Learn more about Thailand’s real-time payment infrastructure, which supports these transactions.
Still, the setup matters. Providers may differ in fees, settlement timing, refunds, and service terms, so owners should check the details before choosing a payment option.
More ways to pay, from cards to mobile wallets
Bank-app QR payments are one option, not a fit for every customer or sale. A shop may also accept cards through a payment terminal, take online payments through checkout software, or support mobile wallets where its provider and merchant account allow them.
Customer preferences vary. A neighborhood shop may see many regular local customers who already use banking apps, while a business in a tourist area may hear more requests for cards or familiar wallets. Age, location, purchase size, and whether the customer lives in Thailand can all shape how someone prefers to pay. For example, the Bank of Thailand announced a cross-border QR payment connection for users from China on October 30, 2025, but the service applies only where the merchant and payment method are supported. Check provider terms rather than assuming a wallet works at every counter.
Faster checkout and clearer sales records
Digital payments can reduce the time spent counting cash, preparing change, and handling deposits. They also create transaction records that make it easier to match customer payments with daily sales, especially when each order has a clear amount or reference.
Those records still need review. Owners should compare payment reports with bank deposits, account for refunds, and subtract provider fees when checking revenue. A QR confirmation is evidence of a transaction, but it doesn’t replace sound bookkeeping or a regular reconciliation routine.
Which digital payment options fit a Thai small business?
The right payment setup depends on where customers buy and how much they spend. A market stall may need a simple QR code, while an online shop or tourist-facing business may benefit from card acceptance and checkout options.
QR payments for shops, stalls, and service businesses
QR payments can suit in-person sales because customers can pay through a participating banking app without cash or a card terminal. A business can display a static QR code on a counter or menu, or use a transaction-specific code that includes the amount due. The available format depends on the bank or payment provider.
Static codes are easy to set up, but staff may need to enter or confirm each sale amount. Transaction-specific codes reduce that step and can make it easier to match payments with orders. Either way, check the account name and payment confirmation before handing over goods or marking a service as paid. A screenshot from the customer is not the same as verifying the payment in the business account or provider app.
Card terminals and payment gateways for larger purchases
A card terminal can help when customers ask to pay by card or when purchases are large enough that carrying cash feels inconvenient. However, terminals may involve equipment costs, transaction fees, and settlement terms, so compare the provider’s total charges before signing up.
Online businesses usually need a payment gateway to process checkout payments. Providers such as Opn (formerly Omise), 2C2P, and GB Prime Pay may support different combinations of cards, QR payments, or wallets. Compare current merchant eligibility, accepted payment methods, settlement timing, and fees. This guide to Thai e-commerce payment gateways offers additional context, and a PromptPay integration overview discusses gateway options.
Online, delivery, and tourist payments
For social media orders or invoices, a payment link can let customers pay without visiting a full online store. Businesses selling through delivery or commerce platforms can also use the payment methods built into those services, though platform rules and payout schedules apply.
Accepting international cards or visitor payment methods may help reach tourists who do not use Thai banking apps. Still, added options can bring processing fees, currency conversion costs, refund requirements, and platform terms. Before enabling a method, confirm directly with the provider that it supports your business, customer locations, and preferred settlement currency.
What Digital Payments Change for Costs, Cash Flow, and Customer Reach
Accepting digital payments affects more than checkout. It changes the costs a business pays to collect money, the timing of cash coming in, and the customers it can serve. Compare the full cost and practical value of each option before adding it.
Compare fees, settlement times, and setup costs
A QR code may be inexpensive to display, while card acceptance can require a terminal purchase or rental. Online payments may add gateway or platform charges. Some QR arrangements have low or no merchant fees, but terms vary by bank, account type, and payment service. Check the provider’s current merchant terms and service charges before signing up.
Also compare what happens after a customer pays. A provider may transfer funds on a different schedule than another, and a business might need a specific bank account or merchant documentation. Refunds can take time to reach customers, while card payments may involve dispute or chargeback costs. Ask providers for a clear breakdown of transaction fees, equipment charges, settlement timing, refund rules, and any account requirements. A method with no terminal cost may still carry other fees.
Use digital sales data to manage cash flow
Transaction histories and daily reports can help owners see when sales peak and which channels bring in the most business. For example, a cafe might find that QR payments rise during lunch, while online orders account for more evening sales. That pattern can guide staff schedules and stock orders.
However, the sales total is not the same as cash available to spend. If a provider settles funds later, or deducts fees before transferring them, account for that gap when planning rent, supplier payments, and payroll. Refunds and chargebacks can also reduce expected deposits. Reconcile provider reports with bank statements regularly, and use the actual payout schedule in cash-flow estimates. Digital transaction data for small-business cash flow can also help owners review payment activity over time.
Reach customers who expect convenient payment choices
Local shoppers may prefer bank-app QR payments, while online customers often expect checkout options that work without visiting a store. Tourists may ask for cards or a supported payment method from their home country. Offering a suitable choice can remove friction at checkout and give customers a reason to return.
More options also mean more fees, setup work, and account requirements. A neighborhood shop with mostly local customers may not need every international wallet, while a tour operator could benefit from card acceptance. Review customer requests and sales records, then add methods that fit the audience and protect margins. For tourism businesses, QR payments for international visitors may offer another way to serve customers who do not use Thai banking apps.
How to Adopt Digital Payments Safely and Choose the Right Setup
A reliable payment setup should fit the way your business sells, protect access to funds, and produce records you can check. Start with a small number of methods, then adjust as you learn what customers use.
Match payment tools to your sales channels
List where customers pay you: at a shop counter, market stall, through social media, on your website, or through a delivery platform. Then choose tools that cover those channels. A QR payment option may work for in-person sales, while a payment link or website checkout can suit online orders.
Start with one or two methods customers already ask for. Before promoting them, test a real transaction, refund, and payout. Check how staff confirm payment and whether the provider’s report matches the amount deposited in your business account. Add another option only when customer requests or sales records justify the extra fees and work.
Protect payments and verify every transaction
Download banking and payment apps only from official sources, and give account access only to staff who need it. Use strong, unique passwords, turn on available security features, and train employees to check payment status in the business app or provider dashboard. A customer’s screenshot alone doesn’t confirm that money reached your account.
Never ask customers to share a password, PIN, or one-time code. Providers and banks should not need those details to complete a payment. For more safeguards, review these payment security practices for businesses.
Plan for outages before they interrupt a sale. Keep a backup option, such as another accepted payment method or a clear process for recording an unpaid order. Tell staff when to release goods and how to reconcile delayed or duplicate payments once service returns.
Keep records and check tax and provider rules
Save transaction reports, receipts, invoices, and records of fees, refunds, and chargebacks. Reconcile these with bank deposits on a regular schedule so you can spot missing payments or mismatched amounts. A Thailand e-Tax invoice record-keeping checklist can help organize invoice details and supporting records.
Tax obligations depend on the business and its circumstances, so confirm requirements with Thailand’s Revenue Department guidance on tax invoices or a qualified accountant. Before opening a merchant account, read the provider’s verification requirements, settlement schedule, fees, refund process, and dispute rules. Keep a copy of the terms you accept, since those rules affect how quickly you receive funds and what happens when a customer challenges a payment.
Frequently Asked Questions
Digital payment requirements and processes can vary by bank and provider. These answers cover common questions to check before setting up payments for a small business in Thailand.
Do small businesses in Thailand need a bank account to accept digital payments?
Usually, a business needs an eligible account to receive and track payments, but requirements depend on the bank, payment provider, and service. Some providers may accept certain personal accounts, while others require a business account or additional merchant registration. Before applying, confirm accepted account types and prepare the required identity and business documents.
Can a small business accept PromptPay without buying a card terminal?
Yes. Many merchants can receive QR payments through a participating bank or payment provider without a card terminal. The setup may use a printed merchant QR code or a provider app, depending on the service. Ask your bank how to register as a merchant and whether fees or other conditions apply.
How quickly do digital payments reach a business account?
Timing varies by payment method, provider, bank, and settlement schedule. A payment may appear in a provider dashboard before the funds arrive in the business account, so check the stated payout terms. Also plan for weekends, holidays, refunds, and any review holds that could delay access to funds.
What should a shop do if the internet or payment service goes down?
Keep a safe backup, such as cash or another approved payment method, and check service status through your bank or provider’s official channels. Staff should verify payment in the business app or account before marking a sale as paid. A written outage process can help employees handle pending orders and reconcile delayed payments; see these payment outage planning tips.
Are QR payments safe for merchants and customers?
QR payments through official banking and provider channels can reduce risk, but both sides should confirm the recipient and payment status before completing a transaction. Merchants should watch for altered or fake QR codes, while customers should avoid suspicious links and never share account credentials, PINs, or one-time codes. The Bank of Thailand’s payment-fraud safeguards provide further context on efforts to address fraud in Thailand’s payment system.
Conclusion
Digital payments are changing small business transactions in Thailand by giving owners a faster, more convenient way to accept payments and clearer records to review. PromptPay and Thai QR payments can help track sales activity, though digital records are most useful when owners keep them organized and reconcile them with business accounts. These records may also give lenders a clearer view of business cash flow, but they don’t guarantee access to financing. See how Thai QR payments can support business cash-flow records.
The strongest setup is one that matches customers and sales channels. Compare provider fees and settlement rules, protect payment accounts, and test each method before relying on it. Done carefully, digital payments make transactions easier to manage while keeping costs, timing, and security in view.